Categories
Buying, educationPublished October 21, 2026
Pre-Approval vs. Pre-Qualification: What San Antonio Buyers Need to Know
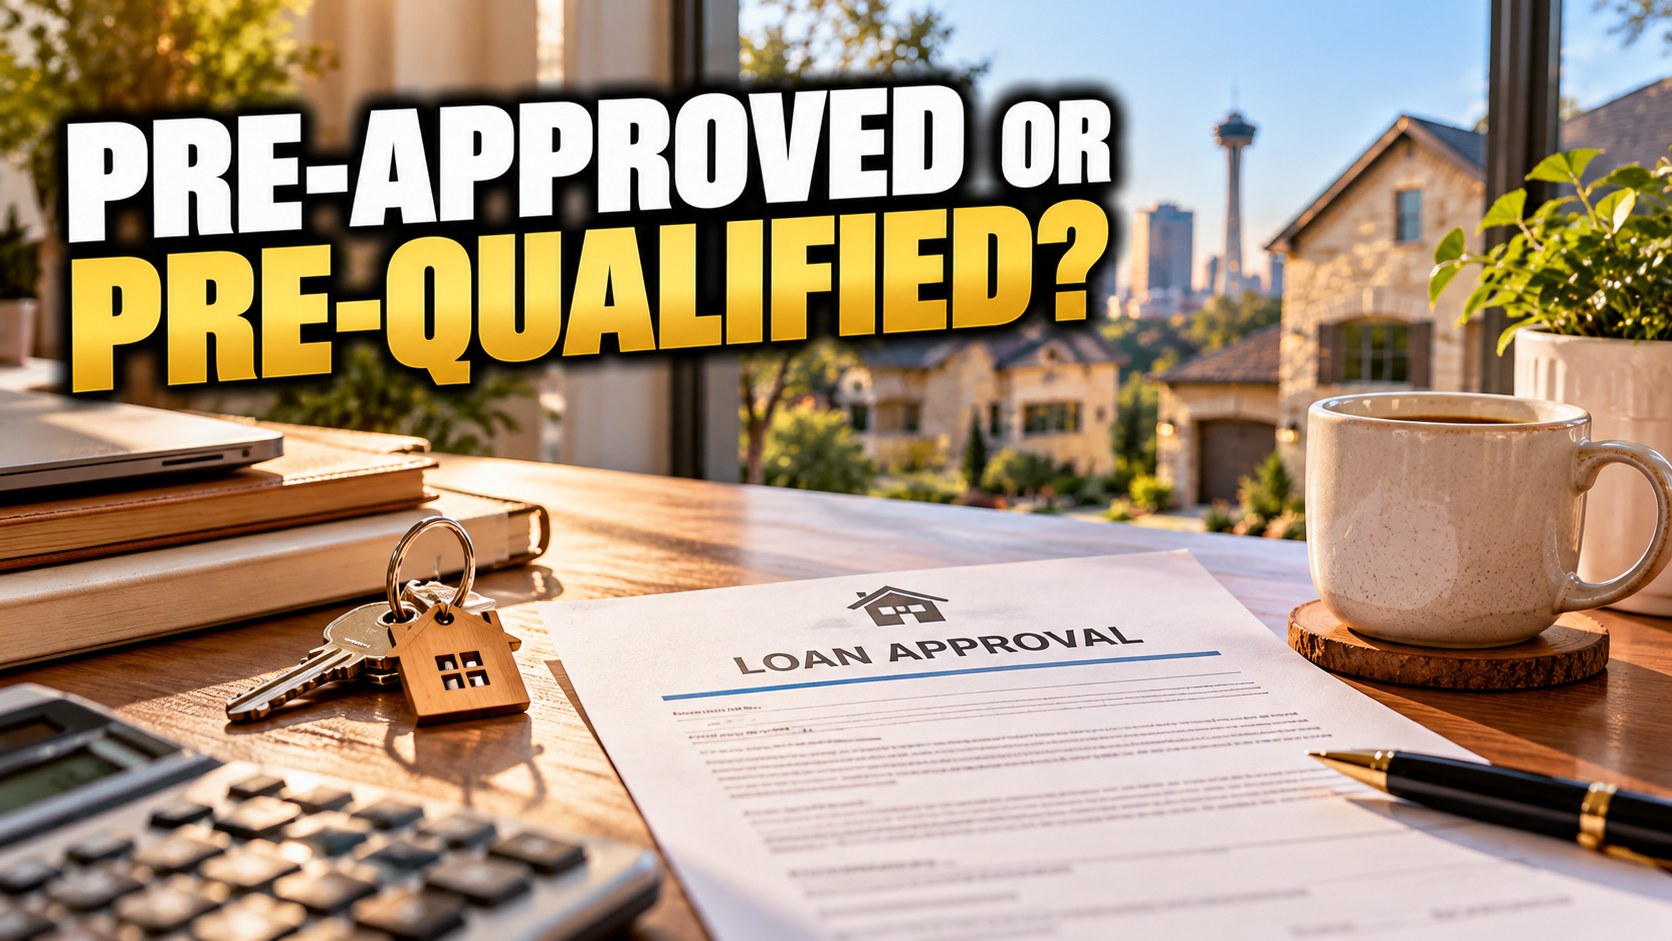
If you are starting to look at homes in San Antonio, you have probably heard both terms: pre-qualified and pre-approved. They sound alike, but in the eyes of a seller they carry very different weight. Knowing the difference can help you shop with confidence and make offers that get taken seriously.
What Pre-Qualification Means
A pre-qualification is a quick estimate. You share some basic information about your income, debts, and savings, and a lender gives you a rough idea of what you might be able to borrow. It is often done in a few minutes, sometimes online, and usually without verifying documents.
It is a helpful first step if you are just curious about your budget, but it is not a commitment from the lender.
What Pre-Approval Means
A pre-approval goes much deeper. The lender reviews your credit, verifies your income and assets with real documents like pay stubs, W-2s, and bank statements, and then issues a letter stating how much they are prepared to lend, subject to final conditions.
That letter tells sellers you have already done the homework and your financing is on solid ground.
Why Sellers Care
It shows you are serious. A pre-approval letter signals that you are ready to buy now, not someday.
It reduces risk. Sellers want to know the deal will close. Verified financing lowers the chance of a surprise later.
It can win in a tie. When two offers are close, the buyer with stronger financing often comes out ahead.
What You Need to Get Pre-Approved
Most lenders will ask for:
- Recent pay stubs and W-2s or tax returns
- Bank and asset statements
- A photo ID
- Permission to check your credit
- Details on any other debts or income
Self-employed buyers may need additional records, so it helps to start early.
Tips Before You Apply
Avoid new debt. Hold off on opening credit cards or financing a car until after closing.
Keep your job steady. Changing jobs mid-process can complicate approval.
Ask about your options. Conventional, FHA, VA, and other programs each have different requirements. A good loan officer will walk you through which fits best.
Ready to Start?
Getting pre-approved is one of the smartest moves you can make before touring homes. If you would like help with the process or want to talk through your options, reach out. We are happy to help you take the first step.
Bradley Burnes
| Burnes International Group - Real Broker LLC
or another way